
Bloc. No K.
That's the first block removed.
A bloc is a group united for a purpose. A block is the thing in your way.
We named the business after both, because you should have the first and not the second.
The blocks we take out.
These are the things that get between people and the lending outcome they’re looking for.
-
The jargon
LVR, DSCR, comparison rate, serviceability. Every term explained the first time it's used, without you having to ask, and without the tone that suggests you should already know.
-
The runaround
Three weeks of silence, then a request for a document you sent in week one. You'll know where your application sits and what's next, without chasing.
-
The raised eyebrow
Self-employed income. A gap in the work history. A structure that doesn't fit the form. Our questions assume the full range of how people actually live and work.
-
The waffle
A straight answer about what we think will happen, including when the answer is no. Said in week one rather than week six.
-
The guesswork
What a lender will want, what it will likely cost, and what stands between you and a yes. Written down, not implied.
-
The one-bank view
Your own bank has one credit policy and one view of you. We have access to over 70 lenders and they each read the same scenario very differently.
A career built on the lending side of the table.
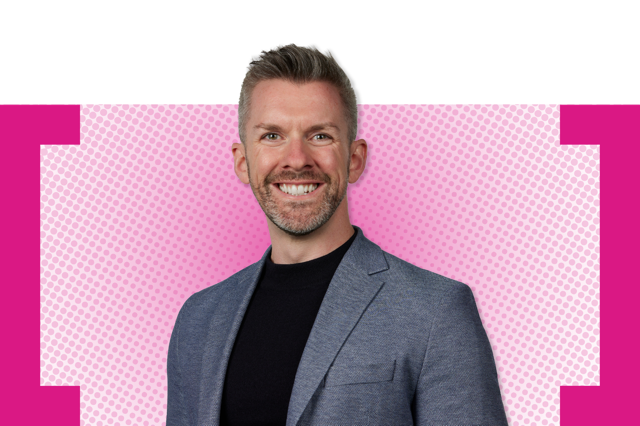
Dan Rhodes-Ryan founded Bloc after sixteen years in banking. NAB, ANZ, then six years at Judo Bank, most recently as Head of Relationship Marketing and before that as a Regional Director.
That's sixteen years structuring and writing deals from the lender's side, and knowing what makes a credit team comfortable enough to approve one. Which lenders will back a business on its trading numbers. Which will stretch on servicing and which won't move. What has to be in front of them before they'll say yes.
That's what Bloc does. We put the application together the way the people assessing it need to read it, and take it to the lender most likely to back it.
We work across home loans, commercial lending and asset finance, because a business owner's borrowing rarely stays in one category for long.
How we work.
-
Say it plain
If you can't repeat it back to someone else afterward, we haven’t done our job properly.
-
Truth early, always
You’ll know where you stand quickly, even if the answer is a ‘not yet’, and what you have to change for it to become a yes.
-
Come as you are
Self-employed income. A gap on the record. A structure that doesn’t fit the form. Our approach considers every possibility.
-
Built to be trusted
We work under an Australian Credit Licence and the obligations that come with it. Those aren't a constraint we work around, they're the thing that makes us worth trusting.
-
In your bloc
You're the dot. We’re part of your bloc, working with you and the right people around you to remove blocks to get you the best possible outcome.
Questions we’re often asked.
-
Bloc Advisory is a finance brokerage based in Melbourne. We arrange commercial and business lending, home loans and asset finance, with access to over 70 lenders.
Most of our clients run businesses, and many others come to us because their situation doesn't fit neatly into a standard application.
We work out how a deal should be structured, put the case together the way a lender's credit team reads it, and manage the application through to settlement, and beyond that.
-
It's spelled Bloc, no K, because a bloc is a group of people united for a purpose. Losing the K is the first block we take out.
-
We’re based in Melbourne and support clients Australia wide. Most meetings happen wherever suits you or over a video call.
-
Both, and asset finance as well. Our commercial background is the specialty, but a large proportion of our enquiries are home loans, including refinances and self-employed applicants whose income doesn't look like a payslip.
-
Each bank has one credit policy that you need to fit in to. We have access to over 70 lenders, including all major banks. They all read a deal differently. Knowing which one will support yours, and why, is our whole job.
-
For home loans: nothing. The lender pays us a commission when the loan settles, and we'll tell you what it is before you apply. Most asset and equipment finance works the same way.
Business and commercial lending is different. There's a fee for us to get started and a second one once a lender puts a formal offer in front of you. Commercial deals can take weeks of work with lenders before they confirm whether they'll support the request, and charging for that work is what lets us dedicate the required time to you. More complex asset finance can carry a work fee for the same reason.
-
Yes. We’ll provide you with a short engagement letter covering what we're doing for you, what it costs (if anything), and what we'll each need from the other.
It also asks that you work with us alone on that deal for an agreed period. Your commitment to our process means you’ll have our full attention while we work through your lending options.
If this sounds like how you'd want to work.
Bloc is built to grow into a group of people who think about this job, and our clients, the same way. If you're a broker, a support person or someone in an adjacent field and this reads like your kind of thing, get in touch.
Nobody shrinks their plans here.
Start with a conversation. Tell us what you're trying to do and we'll tell you where you stand.