General information only. Does not consider your personal situation.
"I'm waiting for the bottom before I buy."
I keep hearing it, and the latest numbers suggest plenty of people feel the same. Nearly 20,000 fewer home loans were written in the September quarter than in the June quarter, and the value of new lending had its biggest fall on record. Here's the catch: the bottom is only an opportunity if you're ready when it comes.
What the numbers say.
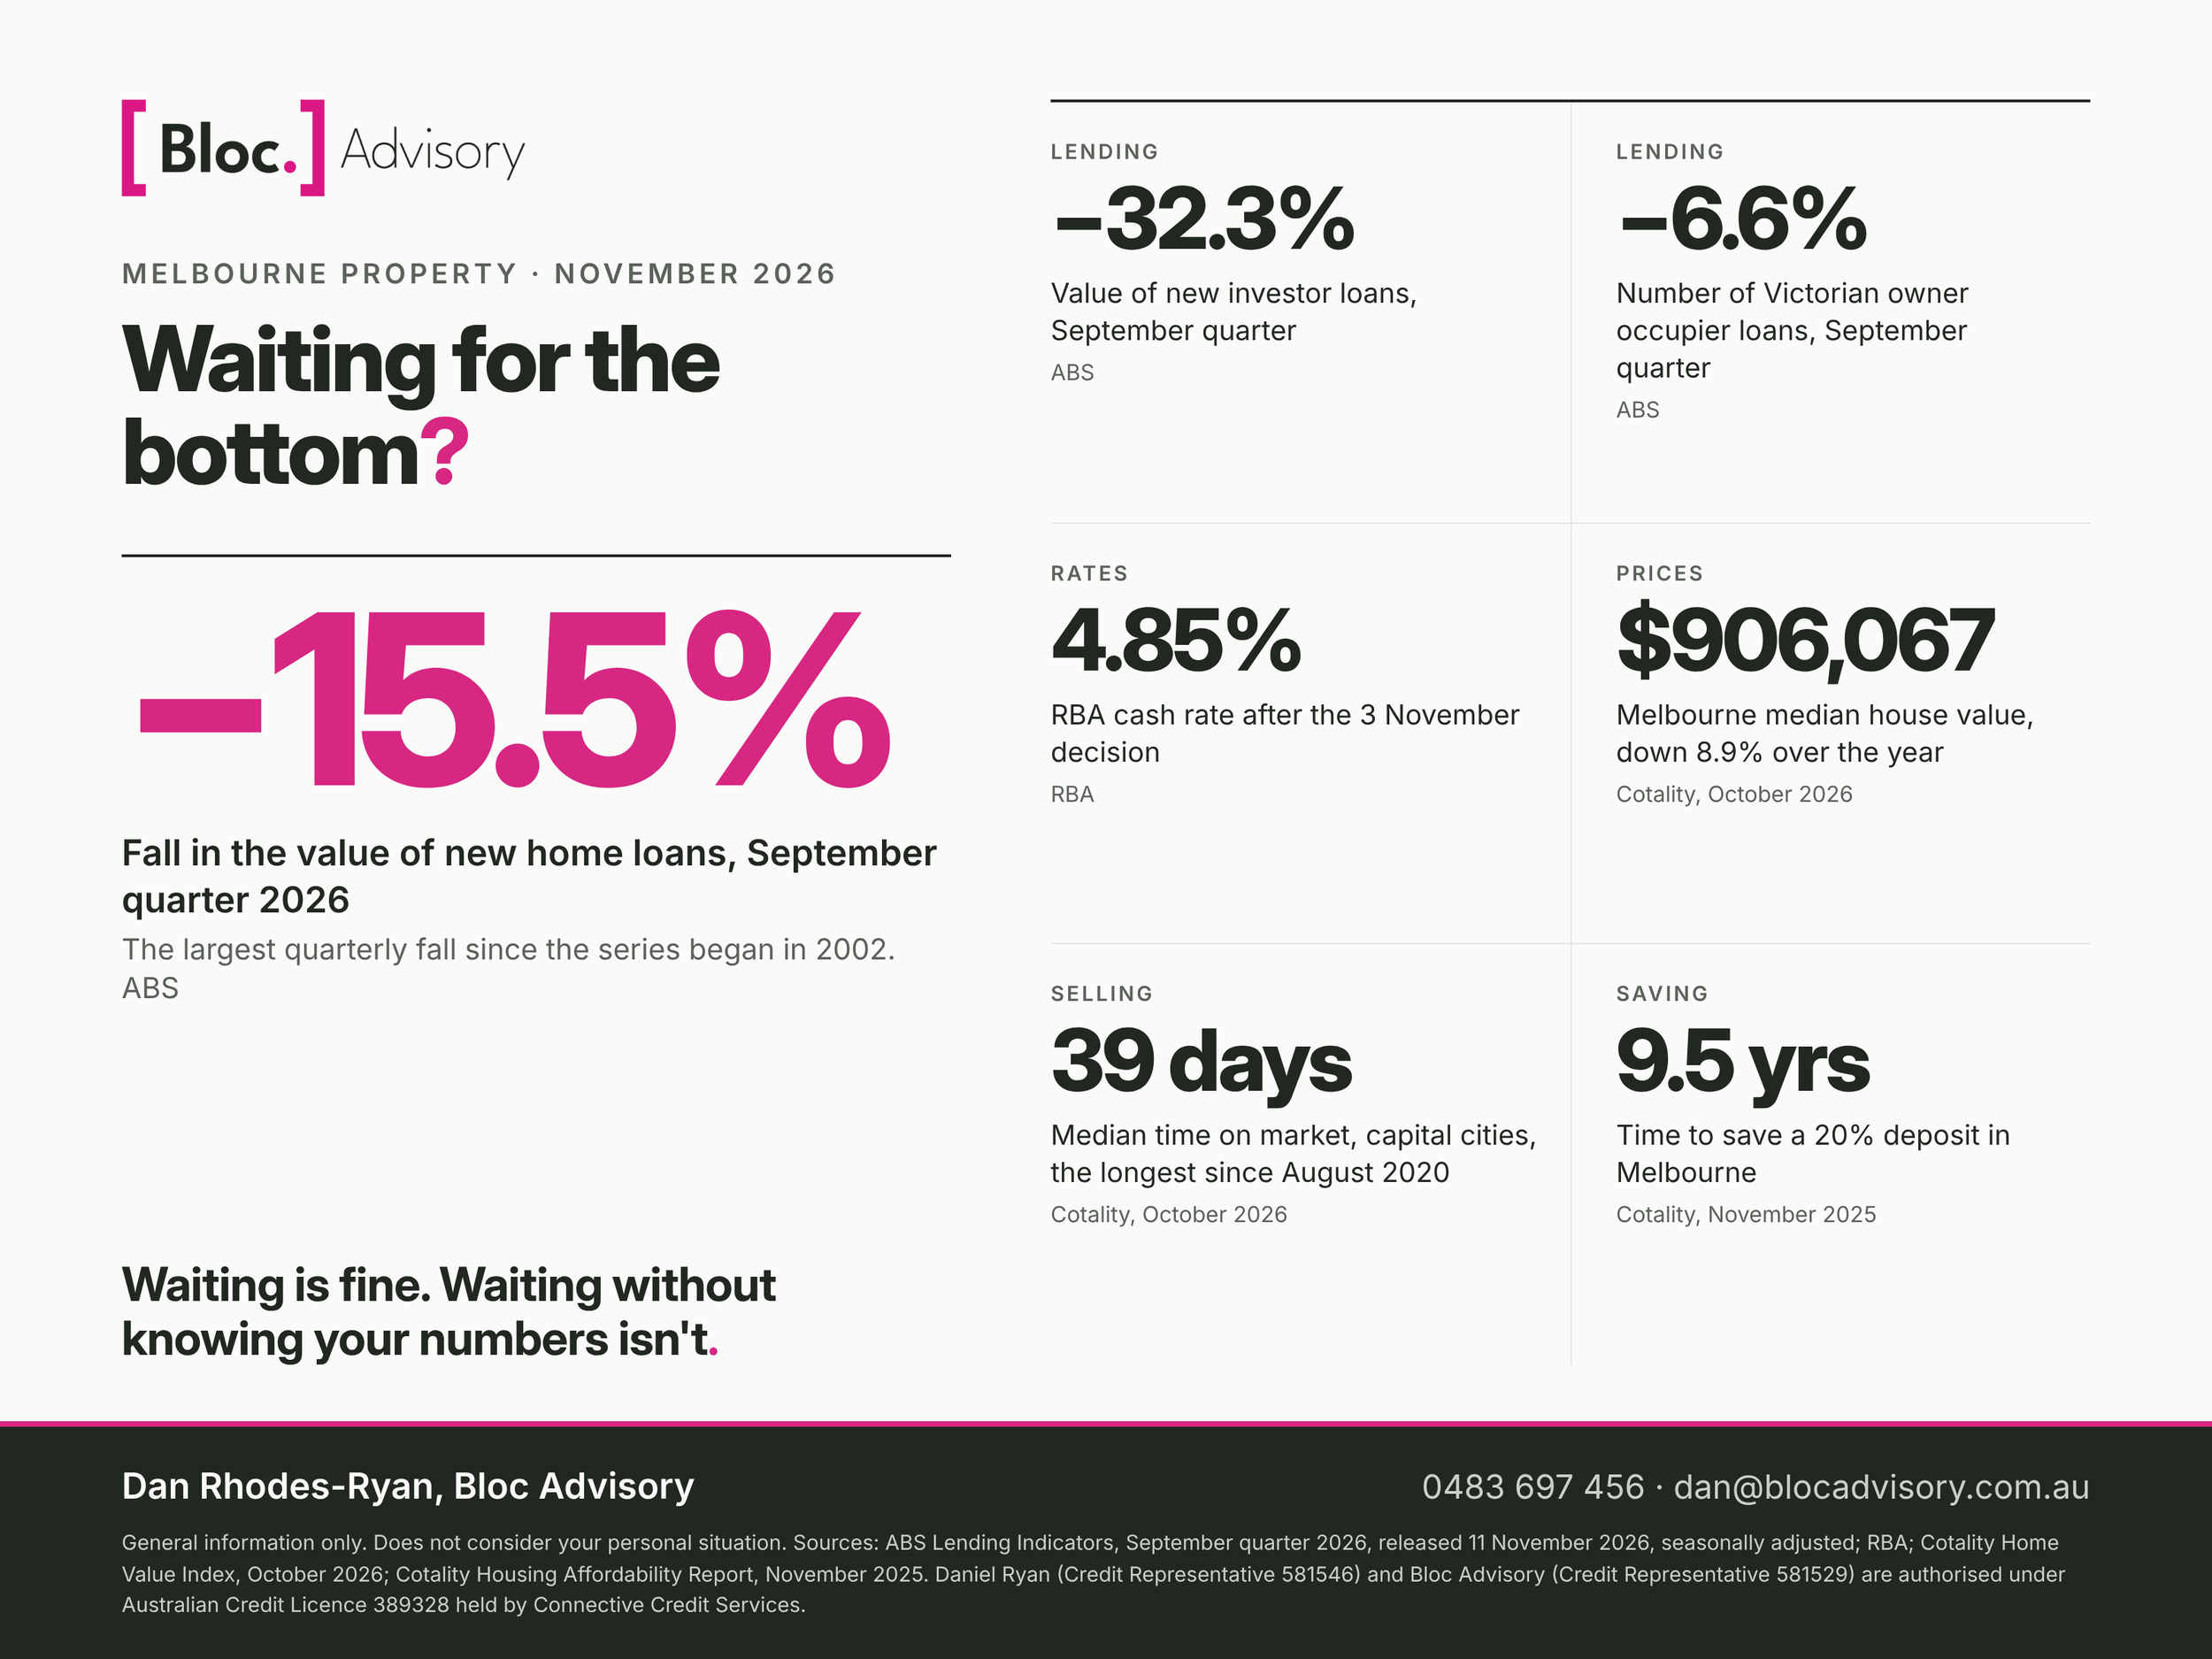
New home loans fell 15.5% in value in the September quarter 2026, the largest quarterly fall on record (ABS, 11 Nov 2026).
New investor loans fell 32.3% in value over the same quarter (ABS).
The RBA cash rate is 4.85% after the 3 November rise (ABC News).
Melbourne's median house value is $906,067, down 8.9% over the year to October (Cotality).
Why it's tougher for sellers.
Buyers can borrow less. Cotality estimates borrowing capacity fell about 11.5% through this year's rises, before November. Someone who could borrow $1 million in January might now be closer to $885,000.
Homes take longer and sell for less. Across the capitals, homes take a median 39 days to sell, and the average discount off the asking price is 4.7%. On a $1 million home, that's about $47,000.
Reserves are now public. Since 16 October, Victorian agents must publish the reserve at least 7 days before auction.
Where buyers might find room.
More choice. Capital city listings are at their highest for this time of year since 2019.
More time. Longer campaigns leave room for inspections, a contract review and a proper look at the numbers.
Less guesswork. With the reserve published a week out, you know the seller's number before you set your limit.
None of this says prices have finished falling. Nobody knows that, me included. It does mean a buyer who's ready can negotiate on their own terms.
Let's be real about the deposit.
Lower prices help, but saving is still the hardest part. Cotality's latest affordability report put the time to save a 20% deposit in Melbourne at 9.5 years, with rent taking 28.1% of household income.
A 20% deposit on a $1 million home is $200,000. Putting away $350 a week, that's 11 years, before stamp duty and costs.
There are ways in with less. Eligible first home buyers can use the Australian Government's Home Guarantee Scheme to buy with 5% down and no lenders mortgage insurance, within price caps. Others pay lenders mortgage insurance to buy sooner. Either way, it's a bigger loan at today's rates, so the borrowing side has to stack up too.
Four numbers to know before you wait.
What you can borrow at today's rate. Lenders test your repayments at a rate above the one you'd pay, so every rise trims your borrowing power first.
What happens if rates rise again. Run it at 0.25% and 0.50% higher.
What you need in cash. Deposit, stamp duty, legals, inspections and a buffer, as one number.
How your file reads to a lender. Self-employed, bonuses or trust income take more explaining. Sort it now.
Example: a $1 million loan over 30 years, principal and interest
At an assumed 6.50% a year, repayments are about $6,321 a month.
At 6.75%, they're about $6,486, or $165 more a month.
At 7.00%, they're about $6,653, or $332 more a month.
Excludes fees and charges. An illustration only, not a rate offer or a forecast.
Waiting is fine. Waiting blind isn't.
I'm not calling the bottom. But I personally think opportunity will come in property at some stage, and you'll want to know where you stand when it does. If you'd like to run your four numbers, reach out.
Dan
Call 0483 697 456 or email dan@blocadvisory.com.au
Sources
Reserve Bank of Australia: Monetary policy decision, 3 November 2026
Cotality: Home Value Index, November 2026 release (October 2026 data)
Cotality: Housing Affordability Report, November 2025
Consumer Affairs Victoria: Selling property by auction
Australian Government, Budget 2026-27: Negative gearing and capital gains tax reform factsheet
Repayment examples are Bloc Advisory calculations for illustration only.
Important information
This article is general information only. It does not consider your objectives, financial situation or needs, and it is not tax, legal or financial advice. Any loan is subject to lender approval. Fees, terms, conditions and eligibility criteria apply.
Bloc Advisory (Credit Representative 581529) and Daniel Ryan (Credit Representative 581546) are authorised under Australian Credit Licence 389328.