Rate Rise November 2026: What It Means for Business Lending.
This Tuesday was our seven year wedding anniversary. Twelve years together. We marked it the way we like to, with a cocktail somewhere nice and then lunch somewhere we always enjoy.
The cocktail was at Gimlet. It was packed. Half past twelve on Melbourne Cup Day, a public holiday with +15% surcharges, and a Tuesday the Reserve Bank was about to put rates up again, and the room was humming. Not a quiet drink before lunch. A proper crowd enjoying drinks and lunches.
Then we walked down the road to Cumulus Inc for lunch and it was very calm and quiet. Lovely, as always, and about half the price for food. Same city, same hour, same weather. One room full, one room barely.
I’ve spent sixteen years understanding businesses and the things they do to survive and I still couldn’t tell you exactly what I saw on Tuesday means. But it’s been on my mind ever since.
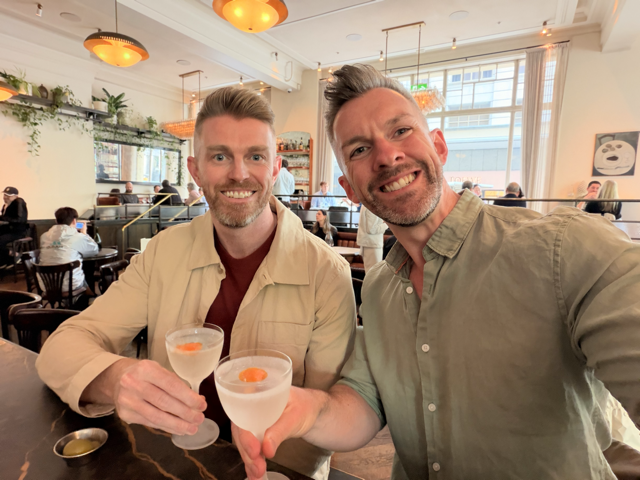
Bloc Advisory founder, Dan, celebrating with his husband, Nick (co-founder of Clarity Medical).
What the numbers actually say.
My instinct walking out of Gimlet was that people are spending like the economy is humming along. Have people decided the dream of owning a property is so far out of reach that they might as well spend their money on a good time? I wouldn’t blame them. Maybe that’s part of what’s happening. The data is more interesting than that.
Household spending was up 6.8% through the year to August 2026. But month on month it was flat, and discretionary spending actually fell 0.3%. Hotels, cafes and restaurants rose 0.8% for the month while most other categories went backwards.
So the honest read is not that everyone is spending freely. It is that people are still spending on the things they can feel, on a table and a room and an afternoon, while trimming elsewhere. Which is roughly what a packed cocktail bar and a calm restaurant at half the price looks like.
The bit I keep coming back to.
Since 2008, capital city house prices have risen about 157%. Median household income, about 87%.
Sit with that gap for a second. Nearly twenty years of it. For most of that time the thing filling the gap has been borrowing capacity, and borrowing capacity is exactly what has been shrinking this year.
I am not going to tell you what is in other people's heads. But if you had spent a decade watching the distance between what you earn and what a house costs get wider every year, I would understand the decision to stop running at it and go and have a nice lunch instead. That’s not recklessness. That is a reasonable response to arithmetic.
Then Tuesday happened.
The Reserve Bank lifted the cash rate to 4.85%. Fifth rise this year, highest in eighteen years, and the board was split six to three. Inflation is expected to stay above 3% over the coming year and not reach the top of the target band until late 2027. Yes, that’s what the economists are saying.
If you run a business you wear the rise twice. Once on the house. Once on the business debt. And if the business debt sits behind the house, that is one asset carrying both.
It lands in a month where the money is already slow. An invoice at seventy days you have chased twice. A supplier increase you absorbed. Someone good who asked for a rise and got it, because they earned it.
What I would actually look at.
Here’s the part I learned on the other side of the desk, across sixteen years lending to businesses at NAB, ANZ and Judo.
The cashflow pressure I saw on business owners was almost never about the rate. The rate plays its part. But far more often it was about how the debt was originally put together. It made sense at the time. Then the business changed, and nobody went back to look.
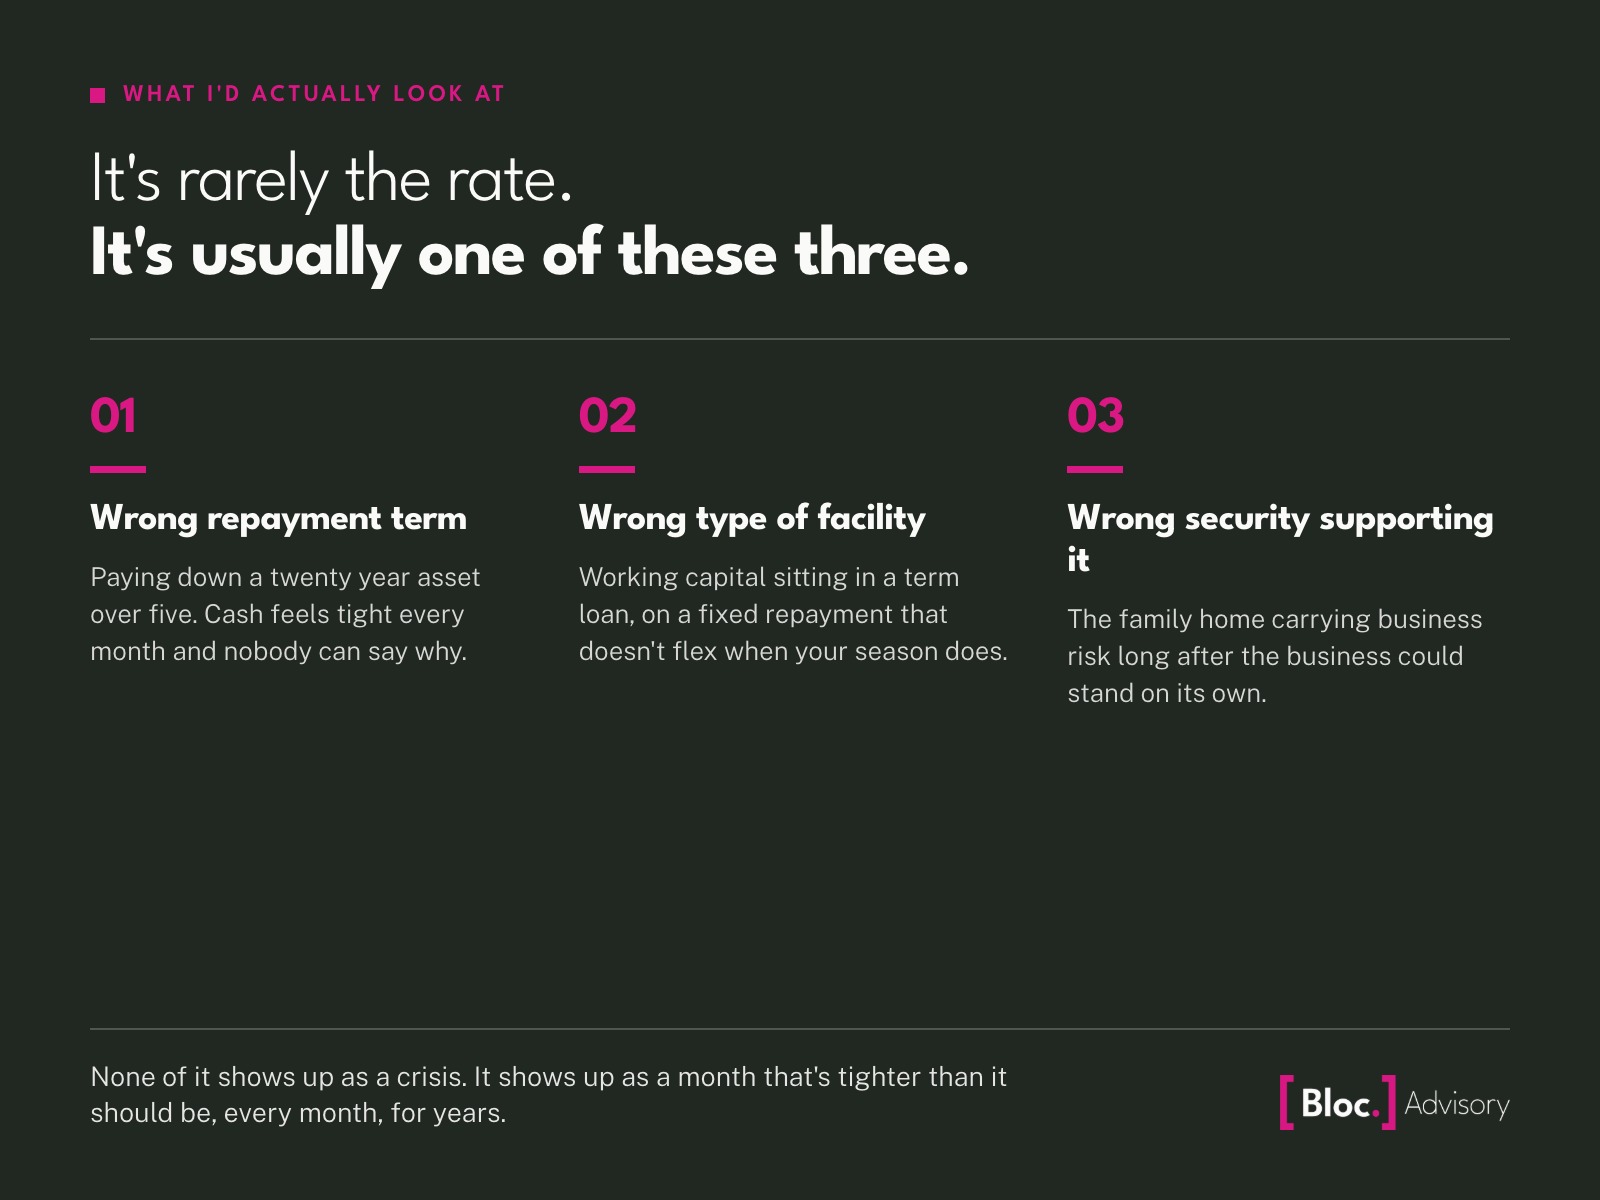
Wrong repayment term, so you are paying down a twenty year asset over five years and wondering why cash is tight.
Wrong type of facility, so working capital that should sit in a line is sitting in a term loan with a fixed repayment that does not flex when your season does.
Wrong security supporting it, so the family home is carrying business risk it was never meant to carry, long after the business could stand on its own.
None of that shows up as a crisis. It shows up as a month that is tighter than it should be, every month, for years.
You cannot do much about the rate. You can do plenty about the structure.
You're often the first to see a client's cash flow tighten. If a client's loan repayments, covenants or ATO obligations are starting to bite, a lending review can sit alongside the advice you're already giving.
I'm happy to work through scenarios with you and your clients, and to keep you informed throughout.
Where this leaves me.
Tuesday was a beautiful day of celebration for us, but this post doesn’t have a tidy ending. It was definitely a strange day to be celebrating something. A full bar, a quiet restaurant, a rate decision in the middle of it, and the two of us talking about a genuinely incredibly twelve years and what the next twelve look like.
What I do know is that the people I see come through these economic circumstances the smoothest aren’t the ones who picked the bottom of the rate cycle. They were the ones who knew what they had to plan for, and got to work doing that.
If you want to know where you stand with your lending, send me a message with what the loan is for and roughly what’s owed. Let’s have that discussion and keep your plan moving.
You can reach me on 0483 697 456 or email dan@blocadvisory.com.au.
General information only. It does not consider your objectives, financial situation or needs. Written 5 November 2026.
Sources
ABS Monthly Household Spending Indicator, Aug 2026
RBA Monetary Policy Decision, 3 Nov 2026
REIA weighted capital city median, Dec 2008 to Jun 2026
ABS 2007 to 08 median gross vs REA modelled FY2025 to 26 estimate
Important information
This article is general information only. It does not consider your objectives, financial situation or needs, and it is not tax, legal or financial advice. Any loan is subject to lender approval. Fees, terms, conditions and eligibility criteria apply.
Bloc Advisory (Credit Representative 581529) and Daniel Ryan (Credit Representative 581546) are authorised under Australian Credit Licence 389328.